Investment strategy: Ditch the ‘investment buckets’!
Flash #70, November 5, 2026
‘You tell us your investment goals, and we provide you with our investment solutions / investment ideas to match.’ This (seemingly) client-centric advisory credo has become established at many banks and asset managers. Even among experts, this advisory approach has made a name for itself under the term ‘goal-based investing’.
A rough example might look like this:
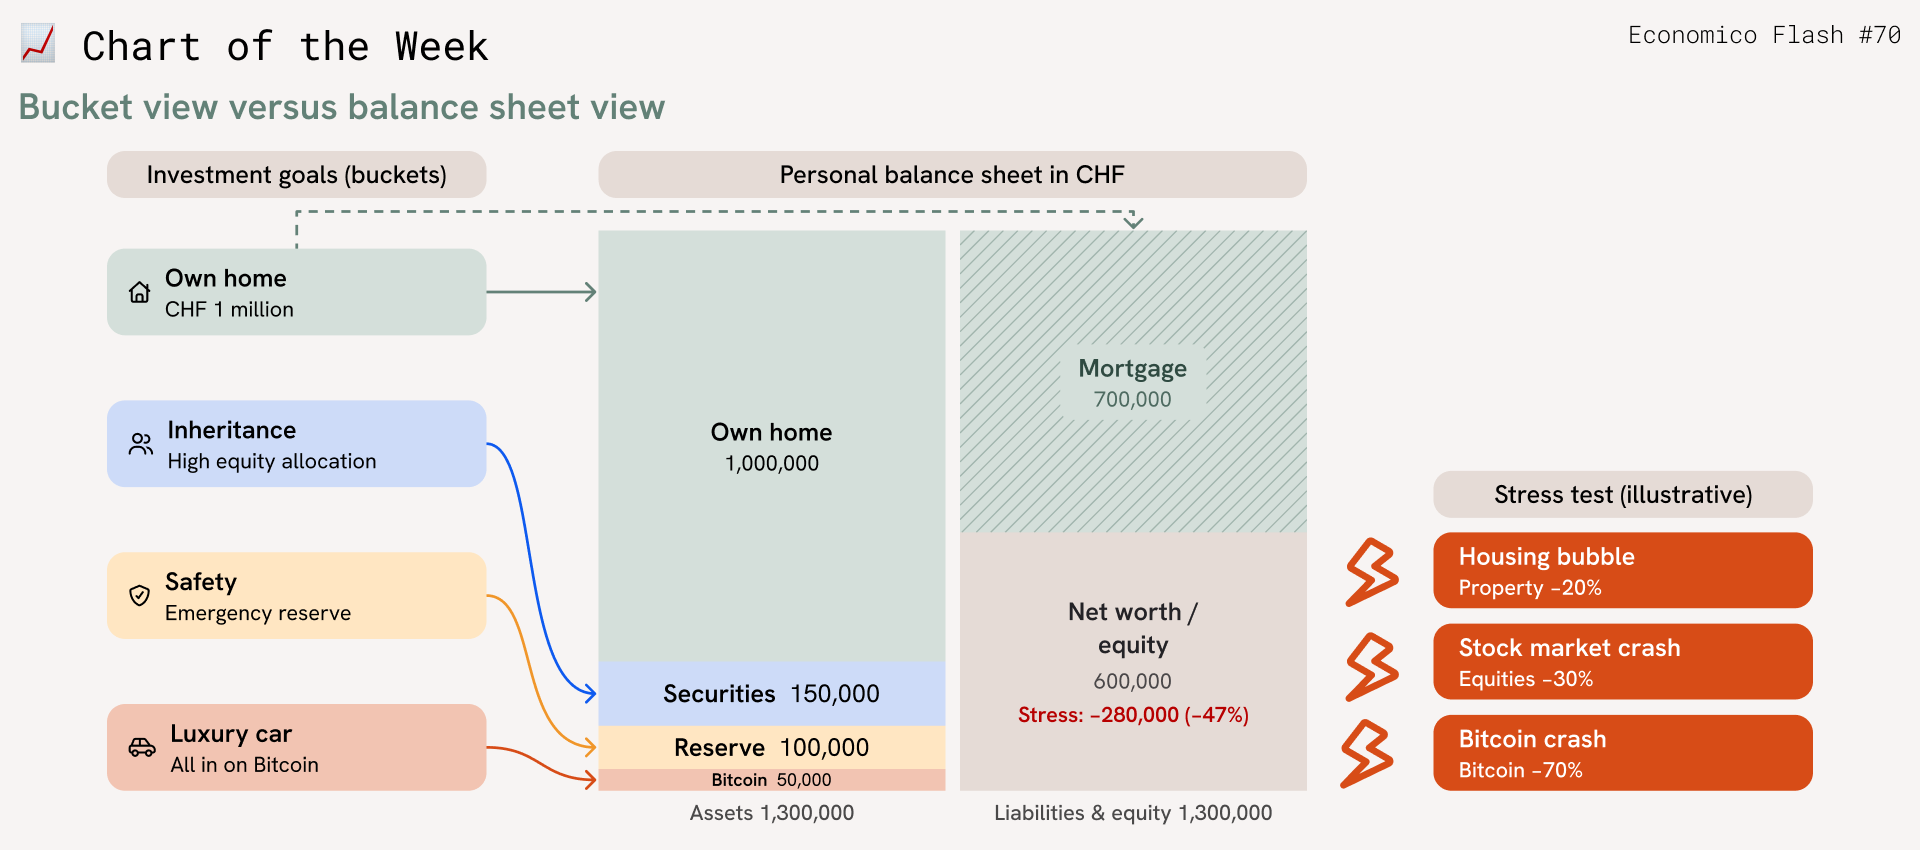
- The investment goal ‘own home’ leads to an early withdrawal from the pension fund and a mortgage from the bank.
- The investment goal ‘inheritance’ leads to a securities solution with a high equity allocation.
- For the investment goal ‘luxury car’, you have to go all in with a Bitcoin investment.
- The investment goal ‘safety’ is addressed with an emergency reserve of CHF 100,000 in a bank account.
The bucket approach sounds client-centric and sells well. Economically, though, it is a detour at best and a dead end at worst. After all, every bucket ultimately ends up on your personal balance sheet and affects your net worth in exactly the same way. A franc in the ‘inheritance’ bucket is worth just as much as a franc in the ‘car purchase’ bucket. When the stock market falls, it is not one bucket that becomes poorer – it is you, the investor.
Bucket logic leads to an arbitrary overall allocation. It is the sum of many individual decisions. Nobody checks any longer whether the resulting overall risk is appropriate. Diversification and costs suffer. Correlations between the buckets are ignored; more buckets mean more transactions and fees.
The alternative is asset liability management (ALM) for private individuals. Incidentally, such a holistic financial view is actually also what the legislator requires as part of the suitability assessment under Art. 12 FinSA. Pension funds serve as a role model: they do not define their investment policy separately for old-age pensioners, disability pensioners or active members either, but take a consolidated view of the overall financial situation.
The ALM approach still leaves plenty of room to name your investment goals explicitly, quantify them and place them on a timeline. Ideally, assign each of them a spending priority right away – human hedonism tends to make investment goals exceed the available budget. A holistic view in a balance sheet context makes such budget constraints visible.
In the upcoming Economico Flash 71, we will present a concrete proposal for how risk profiling and strategy definition can be designed for private individuals.
Takeaways
Investment bucket approach:
- Client-centric and sexy: YES
- Economically consistent: NO
Takeaways
Investment bucket approach:
- Client-centric and sexy: YES
- Economically consistent: NO